When you need funds for major expenses, a home equity loan near Syracuse, NY makes plans and big bills affordable with financing backed by the equity you've built in your home. Whether you're planning a kitchen renovation, consolidating high-interest debt, or covering education costs, we offer competitive home equity loan rates and the personalized service you expect from SECNY FCU. At SECNY, we are powered by real Human Interaction, by people who live and work in Central New York. Come say "HI" to us today!
What is a Home Equity Loan?
 A home equity loan is a second mortgage that allows you to borrow against the value you've built up in your home. You receive the full loan amount upfront as a lump sum and repay it over a fixed term with a predictable monthly payment at a fixed interest rate. This makes budgeting simple and straightforward, with no surprises down the road.
The amount you can borrow depends on your available home equity, which is calculated as your home's current appraised value minus what you still owe on your primary mortgage. SECNY offers home equity loans for up to 90% of your home's value, giving Syracuse area homeowners substantial borrowing power.
HELOC vs Home Equity Loan
Both home equity loans and home equity lines of credit (HELOCs) let you tap into your home's equity, but they work differently and serve different financial needs. Here's a side-by-side comparison to help you decide which option is right for you:
| Feature | Home Equity Loan | HELOC |
| How You Receive Funds | Lump sum at closing | Draw as needed up to credit limit |
| Interest Rate Type | Fixed rate | Variable rate |
| Monthly Payment | Fixed amount, predictable | Varies based on amount borrowed |
| Interest Charged On | Full loan amount from day one | Only the amount you actually use |
| Repayment Structure | Immediate principal and interest payments | Principal + interest |
| Typical Term Length | 5-15 years | 10-year draw period + 15-year repayment period |
| Best Used For | One-time expenses with known costs | Ongoing expenses or variable costs |
| Access to Additional Funds | Not available (must refinance or apply for a new loan) | Available during draw period as you pay down balance |
| Payment Predictability | Same payment each month | Payment fluctuates with balance and rates |
For Syracuse homeowners who prefer predictability and have a one-time expense, a home equity loan often makes more sense. If you need ongoing access to funds, a HELOC may be the better choice.
Is a HELOC or Home Equity Loan Best for You? Get Answers to Your Questions
Competitive Home Equity Loan Rates near Syracuse, NY
Home equity loan rates have become increasingly attractive for Central New York borrowers. Current home equity loan rates are significantly lower than credit cards or personal loan rates, making home equity loans an affordable way to finance major expenses. Your actual rate depends on factors including your credit score, loan amount, loan-to-value ratio, and the equity available in your home.
As a member-focused credit union, we work hard to offer competitive home equity loan rates that save you money over the life of your loan. Our loan officers take the time to review your financial situation and help you find the best home equity loan rate available based on your qualifications.
Ready to see what you could save? Use our home equity loan calculator to estimate your monthly payment and see how much you could borrow based on your home's value. This tool gives you a quick snapshot of your borrowing power and helps you plan your budget before you apply.
What Can You Use a Home Equity Loan For?
One of the biggest advantages of home equity loans is their versatility. Once approved, you can use the funds for virtually any purpose. Syracuse area homeowners commonly use home equity loans for:
Home Improvements and Renovations
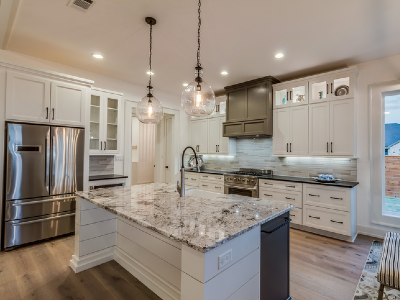 Whether you're updating an outdated kitchen, adding a bathroom, replacing your roof, or finishing your basement, a home equity loan provides the funds you need to increase your home's value and comfort. Many homeowners in the Syracuse area use equity loans to make their homes more energy-efficient by installing new windows, upgrading HVAC systems, or adding insulation.
Debt Consolidation
If you're carrying high-interest credit card debt or multiple loan payments, consolidating with a home equity loan can simplify your finances and save you money. With rates much lower than credit cards, you can pay off existing balances and reduce your monthly obligations to a single, manageable payment.
Education Expenses
From college tuition to trade school costs, education is a significant investment. A home equity loan offers an alternative to student loans, often with more favorable terms and the ability to borrow larger amounts.
Apply Online for a Home Equity Loan
Major Purchases
Need a new vehicle, boat, or RV? Planning a wedding or dream vacation? Home equity loans give you the buying power to make major purchases without draining your savings.
Emergency Expenses
Unexpected medical bills, urgent home repairs, or other financial emergencies can strain your budget. A home equity loan provides quick access to funds when you need them most.
How to Get a Home Equity Loan near Syracuse, NY
Applying for a home equity loan at our credit union is straightforward. Our experienced loan team guides you through every step of the process:
- Check Your Equity - Calculate your home's value minus what you owe
- Gather Documentation - Pay stubs, tax returns, insurance, and mortgage info
- Submit Application - Apply online or by visiting one of our convenient branch locations
- Appraisal - We order a professional evaluation of your home
- Underwriting - We review your credit, income, and property value
- Closing - Sign documents and receive your home equity loan in a lump sum
Why Choose a Local Credit Union for Your Home Equity Loan?
 When you work with a Syracuse area credit union for your home equity loan, you're not just another account number. You're a member and an owner. Credit unions are not-for-profit cooperatives, which means we return profits to members in the form of better rates, lower fees, and superior service.
Our loan officers live and work in Central New York. We understand the local housing market and the unique needs of upstate New York homeowners.
You'll work with the same team members throughout the process, not a rotating cast of representatives in a distant call center. We take time to understand your goals and provide honest guidance about which loan product best fits your needs. Our commitment is to help you make informed financial decisions that strengthen your long-term financial health.
Current Home Equity Loan Rates and Terms
We offer flexible loan terms to match your budget and goals. Choose from 5-year, 10-year, 15-year, or 20-year repayment terms. Shorter terms mean higher monthly payments but less interest paid over the life of the loan. Longer terms offer lower monthly payments with more time to repay.
Your interest rate remains fixed throughout your loan term, protecting you from market fluctuations. You'll know exactly what you owe every month, making it easier to budget and plan for the future.
Rates are personalized based on your creditworthiness, loan amount, and property value, so we encourage you to speak with a loan officer about your specific situation.
Current Home Equity Loan Rates
Turning Plans to Reality Starts with a Home Equity Loan
Whether you're planning a home improvement project, consolidating debt, or need funds for another significant expense, a home equity loan near Syracuse, NY offers an affordable, flexible solution. Our team is ready to help you explore your options and find the right loan for your needs.


